
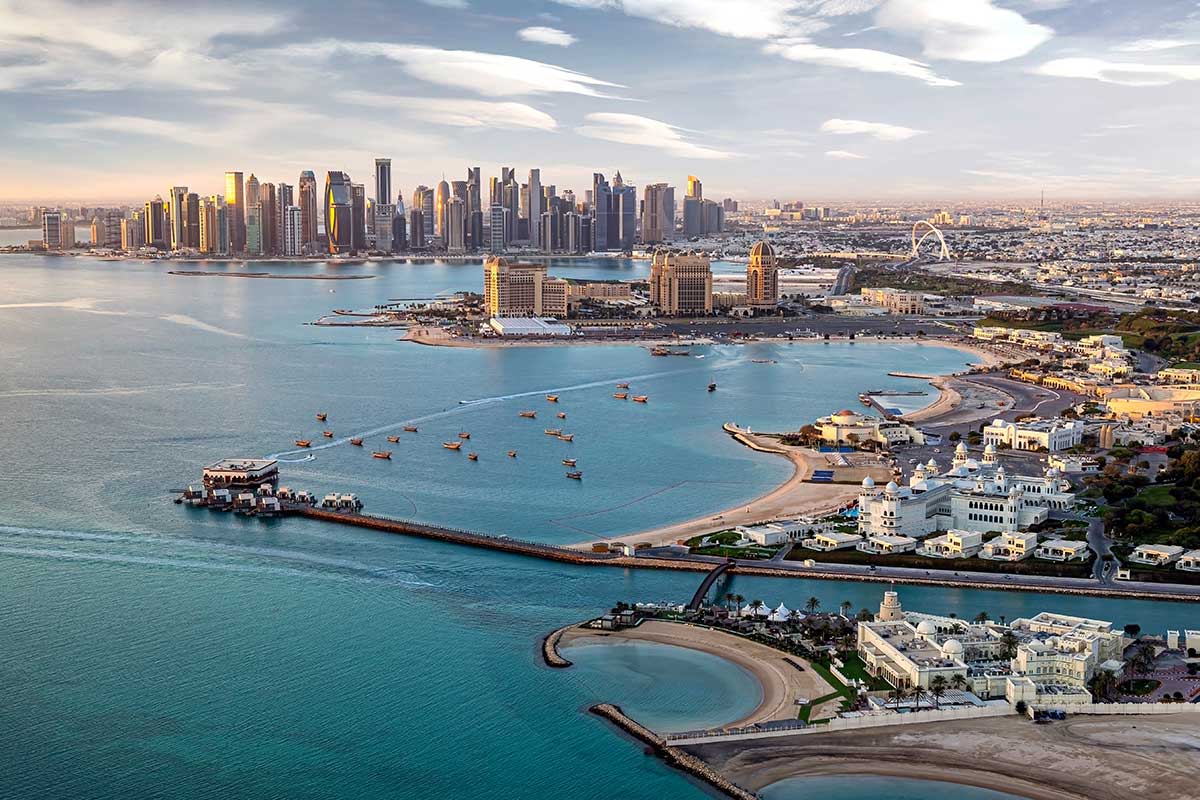
The Qatar real estate market exhibited notable stability in the first quarter of 2025, with various property sectors presenting mixed performance indicators. According to the latest Qatar Real Estate Review, the ValuStrat Price Index (VPI) for residential capital values remained unchanged, highlighting a resilient landscape despite economic fluctuations. The report reveals critical insights into residential transactions, rentals, and overall market dynamics, pointing to both challenges and opportunities in the ongoing evolution of Qatar real estate.
The ValuStrat Price Index (VPI) for residential capital values held steady at 96.5 points in Q1 2025, the same as the previous quarter and the year prior. This index uses Q1 2021 as its reference point of 100.
Anum Hassan, Head of Research at ValuStrat Qatar, remarked, “The first quarter of 2025 reflected a broadly stable real estate landscape in Qatar, with most sectors experiencing either consolidation or modest downward adjustments.”
Mixed Trends in Qatar Property Market
Apartment capital values remained stable at QAR 10,420 per square metre over the past year. The Pearl Island logged sale rates of QAR 10,620 per square metre, maintaining the same figure on a quarterly basis but demonstrating a year-on-year increase of 1.6 percent.
Villa prices also held consistent at QAR 5,500 per square metre, unchanged from both the previous quarter and year. However, values have declined 1.5 percent over the past two years. Within different regions, West Bay Lagoon and Old Airport faced decreases of 5.3 percent and 4 percent year-on-year, while Ain Khaled saw a modest increase of 2.2 percent.
The price-to-rent ratio for both apartments and villas remained stable at 19 years, with the residential gross yield steady at 5.9 percent. Apartments yielded 8.4 percent, while villas achieved 4.6 percent.
Residential transaction volume rose by 13.2 percent quarterly and experienced a dramatic 67.1 percent increase year-on-year in Q1 2025. The median ticket size for housing units was QAR 2.7 million, up 3.8 percent from the previous quarter but down 3.6 percent compared to last year.
The Pearl Island and Al Qassar reported an impressive 54.3 percent surge in sales value, with transaction volume increasing by 39.8 percent quarter-on-quarter. Both Doha and Al Dayeen exhibited the highest levels of transaction activity.
Office Market Dynamics
ValuStrat introduced its new Office Rental VPI in Q1 2025, which encompasses over 90 percent of the national office supply across seven major clusters. The index recorded 97.4 points, indicating a 1.5 percent decline from the previous quarter and a 2.6 percent decrease year-on-year.
The weighted average rents across Qatar settled at QAR 95 per square metre monthly. Grade A offices saw a quarterly reduction of 1.8 percent, averaging QAR 116 per square metre, while Grade B/C spaces remained consistent at QAR 67 per square metre per month.
The office supply expanded by around 60,000 square metres of gross leasable area during the quarter, pushing the overall supply beyond 7.3 million square metres. Notable additions included Marina 31, Corniche Park Towers, and office spaces in Baraha Motor City.
Despite a slight dip in visitor numbers, with Qatar hosting 1.6 million visitors in Q1 2025 mainly from GCC countries—down 6.7 percent year-on-year—hotel occupancy rates averaged 71.3 percent, though this represented a 3.5 percent decline compared to the previous year.
Hospitality and Retail Performance
The Average Daily Rates (ADR) in the hospitality sector fell by 6.4 percent year-on-year to QAR 445, while Revenue Per Available Room (RevPAR) dropped 10.7 percent to QAR 317. Five-star hotels reported an ADR of QAR 522, contrasting sharply with QAR 175 and QAR 220 for three and four-star properties, respectively.
“Tourism remained a strong contributor to economic activity, with 1.6 million visitors recorded—primarily from the GCC,” Hassan commented.
The hospitality stock comprised 40,787 keys, with 68 percent representing four to five-star hotels. An estimated 845 hotel keys are expected to enter the market in 2025, primarily focusing on the four- and five-star segments. Newly opened hotels in Q1 2025 included the Andaz Doha with 256 rooms and Rosewood Doha with 317 keys.
Retail leasing values remained stable during the quarter, with the median monthly rate for shopping centres holding steady at QAR 182.5 per square metre. However, this figure reflects a year-on-year decline of 5.9 percent.
New organized retail space was added with Centro Mall (2,500 square metres) and Outlet Village (30,000 square metres), along with approximately 20,000 square metres of unorganized retail space entering the market in West Bay and Lusail Marina.
The industrial sector showed positive momentum, with ambient warehouse rents increasing by 2.8 percent quarterly to QAR 35.3 per square metre, despite a year-on-year decline of 6.8 percent. Cold storage facility rents also climbed, registering a 3.6 percent quarterly increase and a 5.5 percent annual rise to reach QAR 44.3 per square metre.
Commercial registrations surged by 32 percent compared to Q1 2024, aided by QAR 50 million in industrial investment and the launch of eight new factories. A new ministerial directive allowing company setup through passports and reduced fees for foreign investors drove an impressive 87 percent year-on-year rise in commercial licenses.
The Qatar economy continued to grow, with real GDP increasing by 6.1 percent year-on-year in Q4 2024, reaching QAR 181.1 billion. The International Monetary Fund has projected an average growth rate of 2.4 percent for 2025.
The Qatar Central Bank maintained deposit, lending, and repo rates between 4.6 percent and 5.1 percent in Q1 2025, while the estimated population reached 3.1 million.
The Consumer Price Index for Q1 2025 was stable at 106.9 points annually, though the Housing and Utility index fell by 4.9 percent, while the Communication sector increased by 12.9 percent year-on-year.
The mortgage market recorded 323 transactions across all property asset classes in Q1 2025, reflecting a 2 percent quarterly decline but a substantial 37 percent increase compared to the previous year. The total mortgage transaction value amounted to QAR 9 billion, showing a significant quarterly drop of 63 percent and a year-on-year decline of 45 percent.
Median monthly rents for residential units remained steady from the previous quarter but fell by 1 percent year-on-year to QAR 8,500. Apartment lease values stabilized at QAR 6,000, while reflecting a 2 percent annual drop.
A total of over 18,000 apartment rental contracts were signed in Q1, marking a 15 percent increase on both quarterly and yearly bases. New lease agreements constituted 82 percent of total contracts, a decrease from 95 percent in the previous quarter.
The median rent for villas held at QAR 11,000, remaining stable from the previous quarter but rising 1 percent from last year. Approximately 6,048 villa lease contracts were signed during Q1 2025, indicating increases of 10 percent quarterly and 13.7 percent year-on-year.
In Q1 2025, the total residential stock reached 401,542 units, comprised of 253,513 apartments and 148,029 villas. Around 2,000 apartments were delivered during the quarter, with notable additions including 690 units at Gewan Island (The Pearl), 377 in Shahad Tower (West Bay), and 676 across Lusail Marina’s FJ Residence, Venice Tower, and Nayef Tower.
“In the months ahead, we anticipate further seasonal adjustments, particularly during the summer period, as the market continues to demonstrate resilience while adapting to evolving dynamics,” Hassan concluded.
In Q1 2025, the Qatar government emphasized the importance of real estate and tourism by implementing initiatives to enhance investment opportunities and streamline regulations. The government allocated approximately QAR 6.2 billion for projects, bolstering foreign contracts by 50 percent while local firm allocations decreased by 36.8 percent.